T. Bailey Asset Management Limited do not provide advice to private individuals.

The information contained on this website is intended to provide information about our products and services and is not intended as investment advice. It is important that you do not rely upon its content to make investment decisions without seeking independent advice.

This website is intended for United Kingdom professional investors and advisers only. Please ensure you read the important legal information.

Weekly Update – Keeping perspective

Weekly Update
Economic Outlook Market Commentary Global Equities

Firmer inflation and strong nominal growth have pushed interest-rate expectations and bond yields higher. This week’s update considers what higher yields mean for equity valuations, and why distinguishing market setbacks from deterioration in underlying businesses remains important.

Firmer inflation and strong economic growth are keeping upward pressure on interest rates and bond yields, which in turn can weigh on share prices. In this environment, we think it is important to separate temporary setbacks from genuine deterioration, and to focus on the earnings and valuations of the businesses behind our holdings.

US consumer prices rose 0.4% in October and core inflation rose 0.3%, both above forecasts. This month's report from the US Bureau of Labor Statistics lacked an annual rate due to last year's government shutdown, which has left a gap in its comparison data. Nonetheless, markets have continued to reassess how far the Fed might raise interest rates, with money markets now expecting a quarter-point hike in December. Oil prices have eased recently, with Brent near ten-week lows as US-Iran tensions have subsided, which may help ease inflationary pressure, but the geopolitical backdrop can change quickly.

Continuing strong nominal growth adds to the case for higher long-term rates. US output grew at an annualised 5.6% in nominal terms in the third quarter, and looks to be supporting higher longer-term yields. The chart below puts that quarterly figure in a longer-term context, comparing nominal growth over five years with the 10-year US Treasury yield.
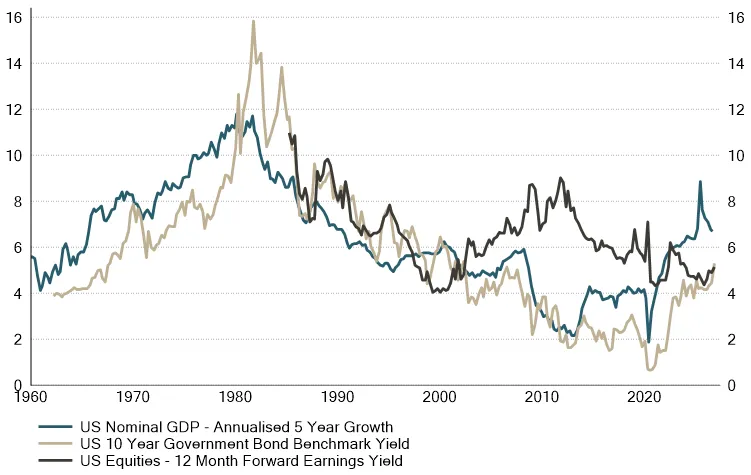
US nominal growth outpacing yields: Annualised 5-year nominal growth

Picture1

Source: LSEG Workspace.

The 10-year US Treasury yield was back above 5% at the end of last week. In addition, higher government-bond yields also raise the return investors require from equities, limiting the valuations they may be willing to pay even when profits are growing. This leaves the more richly valued sections of the market particularly exposed to setbacks, as the sharp sell-off in AI and technology shares has recently shown.

But setbacks should be separated from genuine deterioration. A fall in price is not, in itself, evidence that an investment case has weakened and selling after a sharp decline can mean missing the recovery that follows. The relevant question is whether an investment's prospects have deteriorated, or whether a lower price offers a more attractive opportunity. Higher yields leave less room for valuations that depend on optimistic assumptions about future growth.

These considerations have not prompted substantial changes to our portfolio positioning over October and November so far. Our focus remains on the underlying businesses held by our managers, the sustainability of their earnings and the valuations they are paying, rather than trying to anticipate each change in market sentiment.

Download article as PDF
Back to All Articles