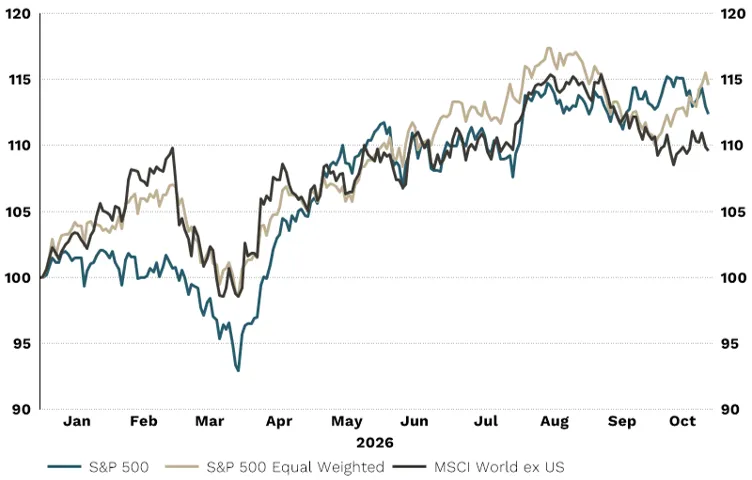
As we touched on in our 1 September weekly update, investors are asking harder questions about the huge sums being spent on AI and whether the future revenues will ever justify them.
For UK-based investors, currency has played its part too. Sterling’s strength against the euro has weighed on returns from unhedged euro-denominated investments. Gold has also had a difficult time, as higher energy prices strengthened the view that US interest rates will stay high for longer.
Last week's reports about the fundraising and listing plans of leading AI developers have brought financing risks back into the spotlight. If money becomes harder to raise, infrastructure projects could be delayed and equipment orders cut back. Even with strong long-term demand, that could mean a difficult spell for suppliers.
The weakness hasn’t been limited to expensively valued companies. Some Asian chip makers have fallen despite modest earnings multiples and strong near-term profit expectations. The question remains how long those profits can be sustained.
We still see room for AI demand to widen as the technology spreads into software, machinery and everyday business processes. TSMC has pointed to more efficient models and wider adoption as sources of further demand. That supports the longer-term case, although broader use would not necessarily quickly make up for a slowdown in US infrastructure spending.
For us, this points to being selective within the AI theme. We see opportunities both in the companies that make the technology and in those that can put it to good use. Our specialist managers help us judge which businesses have the competitive strengths, financial resilience and valuations to withstand less favourable outcomes.
AI isn’t the only place we find opportunity. Attractive businesses can also be found in other investment themes such as healthcare and insurance, whilst value strategies seek out companies whose prospects are being overlooked. These holdings need to earn their place on their own merits, not just serve as an alternative to technology.
Results this week from Alphabet, Amazon and Microsoft will provide another opportunity to assess how revenues, spending and cash generation are developing. The important question is not simply whether AI investment continues to grow, but whether the businesses involved can earn attractive returns from it.