T. Bailey Asset Management Limited do not provide advice to private individuals.

The information contained on this website is intended to provide information about our products and services and is not intended as investment advice. It is important that you do not rely upon its content to make investment decisions without seeking independent advice.

This website is intended for United Kingdom professional investors and advisers only. Please ensure you read the important legal information.

Weekly Update – October in Perspective

Weekly Update
Portfolio Construction Market Commentary Thematic Investing

October brought a change in equity market leadership, with some of the strongest performers of recent years coming under pressure while previously overlooked sectors made gains. T. Bailey Fund Manager, Elliot Farley examines what this means for AI-related investments, why valuations and financing risks remain important, and how exposure to businesses with different sources of growth can support portfolio diversification.

Markets do not need to move in one direction for portfolios to make progress. The challenge is to retain exposure to long-term opportunities without relying too heavily on the same businesses, expectations or sources of growth.

Sector returns for October put numbers to the change in market leadership we covered last week. Several areas that had delivered the strongest gains over three years were among the month’s weakest performers whilst the laggards of recent years made respectable gains.

Technology hardware stands out in the chart below. The sector gained roughly 190% over the three years to the end of October, but fell around 12% during the month.
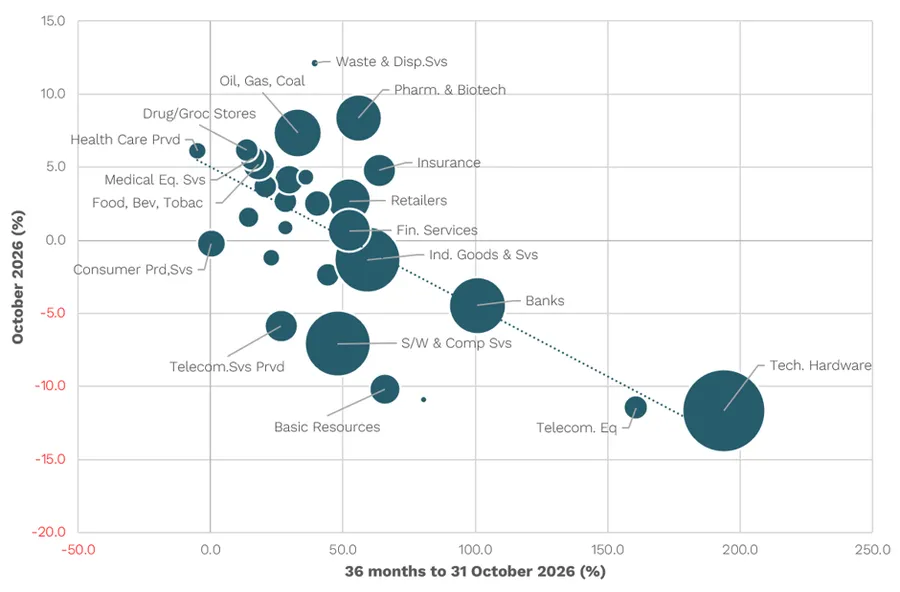
World Sector Performance: October 2026 against 3-year Performance

Bubble sizes are proportional to each sector’s market capitalisation

Picture1

Source: T. Bailey, LSEG Workspace. Total return, GBP terms.

It is too early to call this a lasting reversal. Equity market leadership has changed direction several times this year, and a single month alone is not a reason to overhaul portfolios.

However, AI developer Anthropic’s S-1 filing ahead of its proposed stock-market listing added to the financing questions we raised last week. Rapid revenue growth sits alongside substantial expenses and sizeable computing commitments. Demand for AI is growing, but so is the capital required to deliver it.

While we have not abandoned the theme our exposure to it has steadily shifted towards businesses using AI to improve their operations, alongside selected Asian chip and memory suppliers benefiting from the infrastructure build-out. We see more attractive valuations in these suppliers, reflecting less demanding expectations than in some better-known AI names.

But lower valuations do not insulate them from financing pressures elsewhere in the industry. If AI developers struggle to raise capital, infrastructure spending could slow and demand for chips and memory would consequently suffer. Whilst lower valuations improve the starting point for generating returns, these remain cyclical businesses.

Furthermore, October showed that returns are available beyond the market leaders of recent years. Holdings such as Havelock Global Select, Polar Capital Healthcare Opportunities, Polar Capital Global Insurance and Regnan Sustainable Water and Waste give us exposure to businesses with different earnings drivers. We remain invested in AI’s development, without relying on it as the only source of growth in our investment portfolios.

Download article as PDF
Back to All Articles